Click it and Unblock the Notifications

US Stock Market: DJIA, Nasdaq, S&P 500 Futures Fall On Monday; Wall Street Weekly Outlook For Sept 28 - Oct 2

The US stock market is expected to perform moderately bullish in the trading week from September 28th to October 2nd. However, if treasury yields continue to rise, that could push Wall Street on the downtrend. Last week, the Dow Jones recorded its third weekly decline, while the Nasdaq and S&P 500 indexes ended on a positive note. However, in the early hours of Monday, US stock futures are trading under pressure as investors look for fresh catalysts in the week.
US Stock Futures Today, September 28, 2026
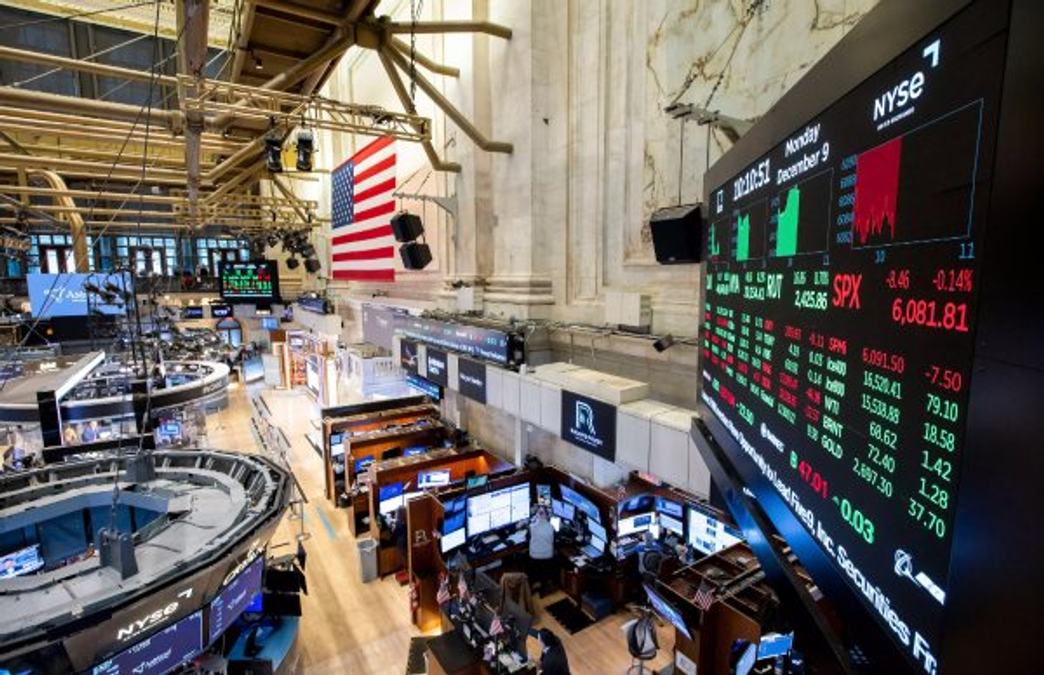
The Dow Jones futures declined by 153 points or 0.3% to trade around at 52,012. The Nasdaq 100 futures dropped by 97.75 points or 0.3% to trade around 30,791.50, while the S&P 500 index slipped by 16.75 points or 0.21% to trade around 7,786.75.
US stock futures declined on Monday as investors looked for fresh catalysts in the week ahead while keeping a close eye on developments in the Middle East. President Trump rejected Iran's latest proposal to reopen the Strait of Hormuz, saying Tehran had overplayed its hand, while adding that he expects negotiations to resume this week. Equity markets remained under pressure from elevated oil prices, which heightened inflation concerns and strengthened expectations for a more hawkish interest-rate outlook, as per Trading Economics report.
The report also highlighted that Treasury yields also climbed to multi-decade highs last week amid expectations of further Federal Reserve tightening and growing concerns over government debt. Investors now turn their attention to the Fed's preferred inflation gauge and key US jobs data due this week. Elsewhere, Trump was scheduled to have dinner with Anthropic CEO Dario Amodei on Sunday, with discussions expected to include the tech executive's recent calls to slow the development of new AI models.
Dow Jones + Nasdaq Composite + S&P 500
On September 25th, Dow Jones index gained by 478.64 points or 0.93% to close at 51,828.62, while Nasdaq Composite index rallied by 129.34 points or 0.5% to end at 27,068.72. Also, the S&P 500 index rose by 39.28 points or 0.51% to close at 7,743.41.
Top performing indexes included hardware shares, hyperscalers, and financial stocks. Applied Materials gained by over 2%, while LAM Research surged nearly 3% and Microsoft zoomed by nearly 4% after plans to merge its consumer and workplace Copilot AI assistants into a product for corporate customers. Further, Alphabet stock gained nearly 1%. On the contrary, Meta stock fell 3.3% but posted weekly gains and Oracle dropped nearly 2%.
The latest rally was also due to benchmark borrowing costs which halted their rising spree after hitting multi-decade highs. Still, the 10 year US treasury yield stood around 5.2%, which is highest level since mid-2007.
However, overall, for the trading week of September 21st to 25th, Dow Jones posted its third weekly decline but marginally down by 108.14 points. In the previous two weeks, Dow Jones have nosedived by more than 1000 points each. On the other hand, Nasdaq Composite recorded weekly gains of 938.52 points or 3.6%, outperforming its counterparts. S&P 500 also followed a positive trend with weekly upside of 50.58 points or 0.7%.
US Stock Market Weekly Outlook For September 28 - October 2
"Next week we'll get quarterly earnings from memory darling Micron Technology, along with the monthly jobs reports next Friday. Nonfarm Payrolls for the prior month came in well above estimates, and if that happens again, or if there is a meaningful pick-up in wage growth (the S&P PMI reports suggested bottlenecks in labor), then this could generate additional upside pressure in Treasury yields," said Nathan Peterson, Director of Derivatives Research and Strategy for the Schwab Center for Financial Research.
According to Peterson, outside of next Friday's employment report, the near-term technicals are relatively bullish, and if Treasury yields pull back (or at least stop moving higher from here), this could help provide a lift to stocks. Additionally, seasonality shifts in the bulls favor as we exit September, and Q3 earnings season is essentially a couple weeks away.
Therefore, he added, "I am providing a "moderately bullish" outlook for next week." What could challenge my forecast? He said, "If Treasury yields continue to push higher at the same rate (five -15 basis points/day) they have over the past three days, or if Friday's Nonfarm Payrolls comes in well above estimates, this could lead to a down week for stocks."
Monday, September 28, 2026
On Monday, there are no economic reports scheduled. However, companies like IDT Corporation (IDT), Jefferies Financial Group Inc. (JEF), NioCorp Developments Ltd. (NB), and Vail Resorts Inc. (MTN) will declare their earnings.
Tuesday, September 29, 2026
Focus will be on economic reports like Consumer Confidence, FHFA Housing Price Index, JOLTs- Job Openings, and S&P Case-Shiller Home-Price Index on Tuesday. While companies like AAR Corp. (AIR), Carmax Inc. (KMX) and Carnival Corporation Ltd. (CCL) are scheduled to declare their earnings.
Wednesday, September 30, 2026
Wednesday will be pivotal for investors sentiment as a host of economic data will be declared such as ADP Employment Change, Advanced International Trade in Goods, Advanced Retail Inventories, Advanced Wholesale Inventories, Chicago PMI, EIA Crude Oil Inventories, Q2 GDP - Third Estimate, MBA Mortgage Applications Index, Personal Consumption Expenditures (PCE) Prices, Personal Income, and Personal Spending.
Among earnings watch out for Cal-Maine Foods Inc. (CALM), Conagra Brands Inc. (CAG), FactSet Research Systems Inc. (FDS), Jabil Inc. (JBL), Levi Strauss & Co. (LEVI), Micron Technology Inc. (MU), and Progress Software Corp. (PRGS).
Thursday, October 1, 2026
The start of October month will also be flooded with major economic data like Construction Spending, Continuing Claims, EIA Natural Gas Inventories, Initial Claims, ISM Manufacturing Index, S&P Global U.S. Manufacturing PMI, S&P Global U.S. and Services PMI.
Earnings will drive market as companies Accenture PLC (ACN), Acuity Inc. (AYI), AngioDynamics Inc. (ANGO), McCormick & Company (MKC), and Nike Inc. (NKE) are scheduled to declare their quarterly report.
Friday, October 2, 2026
On Friday, economic reports like Nonfarm Payrolls, Average Hourly Earnings, Average Workweek, Business Inventories, Factory Orders, and Unemployment Rate are scheduled.
However, only one quarterly result of Trilogy Metals Inc. (TMQ) is scheduled.
Disclaimer: The views and recommendations expressed are solely those of the individual analysts or entities and do not reflect the views of Goodreturns.in or Greynium Information Technologies Private Limited (together referred as "we"). We do not guarantee, endorse or take responsibility for the accuracy, completeness or reliability of any content, nor do we provide any investment advice or solicit the purchase or sale of securities. All information is provided for informational and educational purposes only and should be independently verified from licensed financial advisors before making any investment decisions.

 Sign in with Google